Popular on s4story
- Beyond Wealth and Recognition: Caribbean Author Lyndon Alexander Hall Redefines Success - 214
- Geospatial Innovation Comes to Sacramento: FOSS4G NA 2026 - 213
- New Historical Fiction Book Release - The Legend in the Stone by Cliff Ball - 174
- Sycamore Dove Releases "Loving Every Moment" - 115
- North Carolina Author Carrie Sybert Celebrates Three Published Books - 102
- Architects of Authoritarianism: The Claremont Institute and the Making of the MAGA New Right
- New Children's Picture Book "Adam's Apple" Celebrates Childhood Curiosity and the Funny Misundersta
- When Family Fails, Who Shows Up? Sarah Spector's NEXT BEST THING Offers a Personal Answer
- New Children's Picture Book "Tippy Tay" Explores the Dangers of Peer Pressure and the Importance of
- Award-Winning Author Robert L. Cauley Relaunches Hit Sci-Fi Series Under New Imprint
First Bancorp of Indiana, Inc. Announces Financial Results - September 30 2026
S For Story/10707631
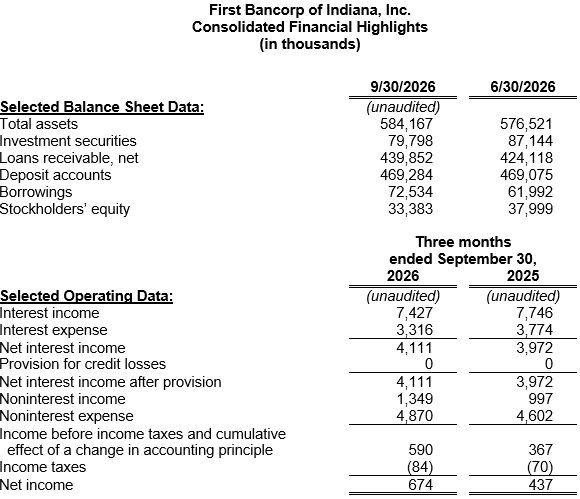
EVANSVILLE, Ind. - s4story -- First Bancorp of Indiana, Inc. (OTCPK:FBPI), the holding company (the "Company") for First Federal Savings Bank (the "Bank"), reported earnings of $674,000 ($0.39 per diluted common share) for the first fiscal quarter ended September 30, 2026, compared to $437,000 ($0.26 per diluted common share) for the same quarter a year ago. Earnings for the three-month period equate to a return on average assets ("ROAA") of 0.47% and a return on average equity ("ROAE") of 7.27%. This compares to an annualized ROAA of 0.29% and an annualized ROAE of 5.21% for the prior year quarter.
"Our first-quarter results reflect continued progress in managing the cost and composition of our funding," stated Michael H. Head, President and CEO. "Stable deposits, reduced reliance on higher-cost brokered deposits, and continued development of core and public funds relationships contributed to lower funding costs and improved net interest margin."
Net interest income for the quarter ended September 30, 2026, improved from the same timeframe last fiscal year. The Company's focus on lowering funding costs more than offset reduced interest income from loans and investments. The Company's net interest margin ("NIM"), measured as a percentage of average interest-earning assets, improved to 3.10% from 2.86% for the prior-year quarter. Noninterest income increased by 35.3% during the most recent quarter, driven by higher service charge income and proceeds from a life insurance claim. Noninterest expense also increased, primarily reflecting higher compensation costs, data processing charges, and professional fees.
The securities portfolio, composed primarily of investment-grade municipal bonds and obligations of U.S. government agencies, totaled $79.8 million at September 30, 2026, compared with $87.1 million at the beginning of the fiscal year. In addition to routine principal repayments, the decrease primarily reflected an increase in the unrealized loss on the Bank's available-for-sale securities portfolio resulting from the recent rise in long-term interest rates.
Net loans outstanding totaled $439.9 million at September 30, 2026, an increase of $15.7 million, or 3.7%, during the quarter. Commercial loan production totaled $15.2 million for the quarter. Single-family mortgage loan production, consisting primarily of loans originated for sale to Fannie Mae or the Federal Home Loan Bank, totaled $5.1 million. Consumer loan originations, including automobile, personal, and home equity loans and lines of credit, totaled $6.2 million.
More on S For Story
No provision for credit losses on loans was recorded in the three months ended September 30, 2026 or 2025. Net loan charge offs totaled $234,900 for the current quarter, compared to $32,700 for the comparative quarter last year. The ratio of nonperforming loans 90 days or more delinquent to total loans was 0.27% on September 30, 2026, compared to 0.29% a year ago.
The allowance for credit losses, including reserves for investment securities and unfunded commitments, stood at $5.11 million at September 30, 2026, compared to $5.28 million on September 30, 2025. The portion of the allowance attributed to the loan portfolio represented 1.12% of at-risk loans on September 30, 2026, compared to 1.13% last year. Management considers the allowance appropriate under current conditions. However, high energy prices, rising interest rates, and elevated inflation could adversely affect borrowers and the credit quality of the loan portfolio. In response, management continues to closely monitor borrowers most affected by these challenges and stands ready to adjust the allowance as needed to address emerging risks.
Total deposit accounts, totaling $469.3 million on September 30, 2026, remained stable from the beginning of the fiscal year, while the Bank continued to retire higher cost brokered deposits. Although local deposit competition has increased in recent months as Treasury rates rose, the focus on core deposits and public funds relationships helped reduce the cost of deposits to 2.32% for the current quarter compared to 2.56% for the same quarter last fiscal year. Similarly, the Company's total cost of funds, including FHLB advances and debt of the holding company, totaled 2.52% for the quarter, compared with 2.70% for the quarter ended September 30, 2025.
As part of the Bank's liquidity management plan, management maintains diversified contingent funding sources and performs liquidity stress testing to assess funding adequacy. At September 30, 2026, the Bank had $22.5 million of unused lines of credit with correspondent financial institutions. Additional secured borrowing capacity included $16.9 million through the Federal Reserve Bank's discount window and $115.6 million through the Federal Home Loan Bank.
Stockholders' equity totaled $33.4 million on September 30, 2026, compared with $35.7 million at September 30, 2025. The year-over-year decline was primarily the result of an increase in the unrealized loss on the Bank's available-for-sale securities portfolio. Based on the 1,712,058 outstanding common shares on September 30, 2026, the tangible book value per share of FBPI stock was $15.86, compared to $17.28 on September 30, 2025.
More on S For Story
On September 30, 2026, First Federal Savings Bank's Community Bank Leverage Ratio ("CBLR") was 9.63%. At September 30, 2025, the Bank reported a Tier 1 leverage ratio of 8.92%.
At its October meeting, the Board of Directors of First Bancorp of Indiana, Inc. declared a cash dividend of $0.08 per share, payable to stockholders of record as of December 1, 2026. The dividend will be paid on or about December 15, 2026. While it is the Board's intent to pay a regular quarterly dividend, the payment of any future dividends will be subject to, among other factors, the Company's and the Bank's financial condition, earnings, and capital requirements.
This press release may contain statements that are forward-looking, as that term is defined by the Private Securities Litigation Act of 1995 or the Securities and Exchange Commission in its rules, regulations and releases. The Company intends that such forward-looking statements be subject to the safe harbors created thereby. All forward-looking statements are based on current expectations regarding important risk factors including, but not limited to: general economic conditions; prices for real estate in the Company's market areas; the interest rate environment and the impact of the interest rate environment on our business, financial condition and results of operations; our ability to successfully conserve and enhance capital levels, enhance liquidity and earnings, and reduce higher funding costs; the Company's ability to pay future dividends; the Bank's ability to pay dividends to the Company to fund the payment of cash dividends on the Company's common stock, and the ability of the Bank to receive any required regulatory approval or non-objection to do so; changes in the demand for loans or in the quality or composition of our loan or investment portfolios; deposits and other financial services that we provide; the possibility that future credit losses may be higher than currently expected as a result of changes in relevant accounting or regulatory requirements, among other factors; competitive pressures among financial services companies; the ability to attract, develop and retain qualified employees; our ability to maintain the security of our data processing and information technology systems; the outcome of pending or threatened litigation, or of matters before regulatory agencies; changes in law, governmental policies and regulations; and rapidly changing technology affecting financial services. Accordingly, actual results may differ from those expressed in the forward-looking statements, and the making of such statements should not be regarded as a representation by the Company or any other person that results expressed therein will be achieved. The Company undertakes no obligation to release revisions to these forward-looking statements publicly to reflect events or circumstances after the date hereof or to reflect the occurrence of unforeseen events, except as required to be reported by applicable law.
"Our first-quarter results reflect continued progress in managing the cost and composition of our funding," stated Michael H. Head, President and CEO. "Stable deposits, reduced reliance on higher-cost brokered deposits, and continued development of core and public funds relationships contributed to lower funding costs and improved net interest margin."
Net interest income for the quarter ended September 30, 2026, improved from the same timeframe last fiscal year. The Company's focus on lowering funding costs more than offset reduced interest income from loans and investments. The Company's net interest margin ("NIM"), measured as a percentage of average interest-earning assets, improved to 3.10% from 2.86% for the prior-year quarter. Noninterest income increased by 35.3% during the most recent quarter, driven by higher service charge income and proceeds from a life insurance claim. Noninterest expense also increased, primarily reflecting higher compensation costs, data processing charges, and professional fees.
The securities portfolio, composed primarily of investment-grade municipal bonds and obligations of U.S. government agencies, totaled $79.8 million at September 30, 2026, compared with $87.1 million at the beginning of the fiscal year. In addition to routine principal repayments, the decrease primarily reflected an increase in the unrealized loss on the Bank's available-for-sale securities portfolio resulting from the recent rise in long-term interest rates.
Net loans outstanding totaled $439.9 million at September 30, 2026, an increase of $15.7 million, or 3.7%, during the quarter. Commercial loan production totaled $15.2 million for the quarter. Single-family mortgage loan production, consisting primarily of loans originated for sale to Fannie Mae or the Federal Home Loan Bank, totaled $5.1 million. Consumer loan originations, including automobile, personal, and home equity loans and lines of credit, totaled $6.2 million.
More on S For Story
- Brian G. Miller Co., LLC Receives Tier 1 Ranking in the 2027 Edition of Best Law Firms®
- The Villari Firm, PLLC Named to the 2027 Edition of Best Law Firms
- A New Take on Shakespeare's Hamlet: L.A. Author Publishes A Tale of Two Hamlets
- Children's Book Series Celebrates Another Holiday!
- Bacchus Wine & Spirits and Michelin Guide–Recommended Ethel's Fancy to Host Exclusive LOUIS XIII Limited Edition Diwali Decanter Celebration
No provision for credit losses on loans was recorded in the three months ended September 30, 2026 or 2025. Net loan charge offs totaled $234,900 for the current quarter, compared to $32,700 for the comparative quarter last year. The ratio of nonperforming loans 90 days or more delinquent to total loans was 0.27% on September 30, 2026, compared to 0.29% a year ago.
The allowance for credit losses, including reserves for investment securities and unfunded commitments, stood at $5.11 million at September 30, 2026, compared to $5.28 million on September 30, 2025. The portion of the allowance attributed to the loan portfolio represented 1.12% of at-risk loans on September 30, 2026, compared to 1.13% last year. Management considers the allowance appropriate under current conditions. However, high energy prices, rising interest rates, and elevated inflation could adversely affect borrowers and the credit quality of the loan portfolio. In response, management continues to closely monitor borrowers most affected by these challenges and stands ready to adjust the allowance as needed to address emerging risks.
Total deposit accounts, totaling $469.3 million on September 30, 2026, remained stable from the beginning of the fiscal year, while the Bank continued to retire higher cost brokered deposits. Although local deposit competition has increased in recent months as Treasury rates rose, the focus on core deposits and public funds relationships helped reduce the cost of deposits to 2.32% for the current quarter compared to 2.56% for the same quarter last fiscal year. Similarly, the Company's total cost of funds, including FHLB advances and debt of the holding company, totaled 2.52% for the quarter, compared with 2.70% for the quarter ended September 30, 2025.
As part of the Bank's liquidity management plan, management maintains diversified contingent funding sources and performs liquidity stress testing to assess funding adequacy. At September 30, 2026, the Bank had $22.5 million of unused lines of credit with correspondent financial institutions. Additional secured borrowing capacity included $16.9 million through the Federal Reserve Bank's discount window and $115.6 million through the Federal Home Loan Bank.
Stockholders' equity totaled $33.4 million on September 30, 2026, compared with $35.7 million at September 30, 2025. The year-over-year decline was primarily the result of an increase in the unrealized loss on the Bank's available-for-sale securities portfolio. Based on the 1,712,058 outstanding common shares on September 30, 2026, the tangible book value per share of FBPI stock was $15.86, compared to $17.28 on September 30, 2025.
More on S For Story
- Arizona Pest Control Surpasses $200,000 in Contributions to Southern Arizona High School Sports and Education Programs
- ZenaTech (NAS DAQ: ZENA) $1 Million in New Utility Contracts- Potential $2.5 Million Follow-On Opportunity Puts Its Drone Business in the Spotlight!
- New Patient Data Show REQORSA® Activating Cellular Repair Pathways as Roche Collaboration Advances Precision Lung Cancer Strategy for Genprex, Inc
- Genuine Hospitality, LLC Selected to Operate Holiday Inn Express & Suites Jacksonville – Town Center
- Denry Okpor Publishes Launch Your Venue, a Practical Playbook for Opening a Salon, Café or Bar
On September 30, 2026, First Federal Savings Bank's Community Bank Leverage Ratio ("CBLR") was 9.63%. At September 30, 2025, the Bank reported a Tier 1 leverage ratio of 8.92%.
At its October meeting, the Board of Directors of First Bancorp of Indiana, Inc. declared a cash dividend of $0.08 per share, payable to stockholders of record as of December 1, 2026. The dividend will be paid on or about December 15, 2026. While it is the Board's intent to pay a regular quarterly dividend, the payment of any future dividends will be subject to, among other factors, the Company's and the Bank's financial condition, earnings, and capital requirements.
This press release may contain statements that are forward-looking, as that term is defined by the Private Securities Litigation Act of 1995 or the Securities and Exchange Commission in its rules, regulations and releases. The Company intends that such forward-looking statements be subject to the safe harbors created thereby. All forward-looking statements are based on current expectations regarding important risk factors including, but not limited to: general economic conditions; prices for real estate in the Company's market areas; the interest rate environment and the impact of the interest rate environment on our business, financial condition and results of operations; our ability to successfully conserve and enhance capital levels, enhance liquidity and earnings, and reduce higher funding costs; the Company's ability to pay future dividends; the Bank's ability to pay dividends to the Company to fund the payment of cash dividends on the Company's common stock, and the ability of the Bank to receive any required regulatory approval or non-objection to do so; changes in the demand for loans or in the quality or composition of our loan or investment portfolios; deposits and other financial services that we provide; the possibility that future credit losses may be higher than currently expected as a result of changes in relevant accounting or regulatory requirements, among other factors; competitive pressures among financial services companies; the ability to attract, develop and retain qualified employees; our ability to maintain the security of our data processing and information technology systems; the outcome of pending or threatened litigation, or of matters before regulatory agencies; changes in law, governmental policies and regulations; and rapidly changing technology affecting financial services. Accordingly, actual results may differ from those expressed in the forward-looking statements, and the making of such statements should not be regarded as a representation by the Company or any other person that results expressed therein will be achieved. The Company undertakes no obligation to release revisions to these forward-looking statements publicly to reflect events or circumstances after the date hereof or to reflect the occurrence of unforeseen events, except as required to be reported by applicable law.
Source: First Bancorp of Indiana Inc
0 Comments
Latest on S For Story
- New Book - Salt On My Tail: A World War II Aviator's Memoir of Brotherhood, Battle, and Barbed Wire
- Club Wyndham Research Identifies the "Holiday Rewind Effect": 93% of Parents Recreate Their Own Childhood Holidays for Their Kids
- New Book - Confessions of a Care Worker: Stories of Disability and Dignity
- Craig Conover's Patch Work Debuts as an Instant New York Times and USA Today Bestseller
- IEI Rugged IP66 Panel PC Brings Real-Time Visibility to Heavy-Duty Mining Fleets
- FDA Approval; Major Milestone for Preservative-Free Ketamine Ahead of FDA Goal Date for Treatment of Suicidal Depression by NRx Pharmaceuticals, Inc
- Building a Technology Powerhouse-From AI Drones and Global Acquisitions to Defense, Enterprise Software and the Future of Autonomous Operations $ZENA
- Shelter Structures America backs MATRA Second Life Project to turn retired tent vinyl into homes for displaced families
- Personal Finance Enthusiast Pete Waitzman Offers Free YouTube Memoir, $0.99 Beginner's Guide Nov 3-9
- P-Wave Press Announces Becoming Dad: Reflections for New Fathers by L. A. Davenport
- Riverside Caregiver Library Featured in New Video from CareVantage Solutions
- Logicraft Launches FuelDeck™, AI That Turns Aviation Fuel Tickets Into One Traceable Ledger
- The Philosopher Who Put Certainty on Trial: Q Unveils New David Hume Series
- Inaugural OC Tech Week Draws 3,000 From 12 Countries, Sends Finalist to $1M Startup World Cup
- Award-Winning American Hotelier Opens Art-Filled Luxury Cottage in Norfolk, England
- K2 Global / Ozi Amanat Named Among Top 100 AI Venture Capitalists in 2026
- Dr. Latorial Faison Appointed Poet Laureate of Virginia
- AdLeverage Brings Golf Simulator Contest and Home Services Marketing Expertise to Service World Expo 2026
- LA Author Akili D. Hight Debuts LUCID Comic, Expands Afrofuturist Universe at LA Comic Con 2026
- Cleveland Factory Worker Seeks Funding for AI-Readable Archive Exploring Advanced AI Restraint and Human Survival